Companion animal caregivers routinely confront agonizing emotional devastation when catastrophic medical emergencies collide with overwhelming veterinary intensive care estimates. When sudden veterinary crises strike—such as acute gastric dilatation-volvulus requiring immediate gastropexy, complex cranial cruciate ligament tears necessitating tibial plateau leveling osteotomy, or aggressive feline gastrointestinal lymphoma—emergency stabilization and specialized surgical interventions routinely exceed four to eight thousand dollars within initial critical hours. Uninsured pet owners forced into the heartbreaking reality of economic euthanasia endure profound, permanent trauma simply because family savings cannot absorb unexpected tertiary hospital expenditures. By systematically deconstructing veterinary insurance underwriting models, evaluating actuarial breed-specific risk curves, and selecting optimized reimbursement-to-deductible policy tiers, guardians establish an impenetrable financial safety net that guarantees medical choices are dictated entirely by clinical prognosis rather than bank balances.
1. The Reimbursement Model Architecture: Underwriting, Deductibles, and Co-Pays
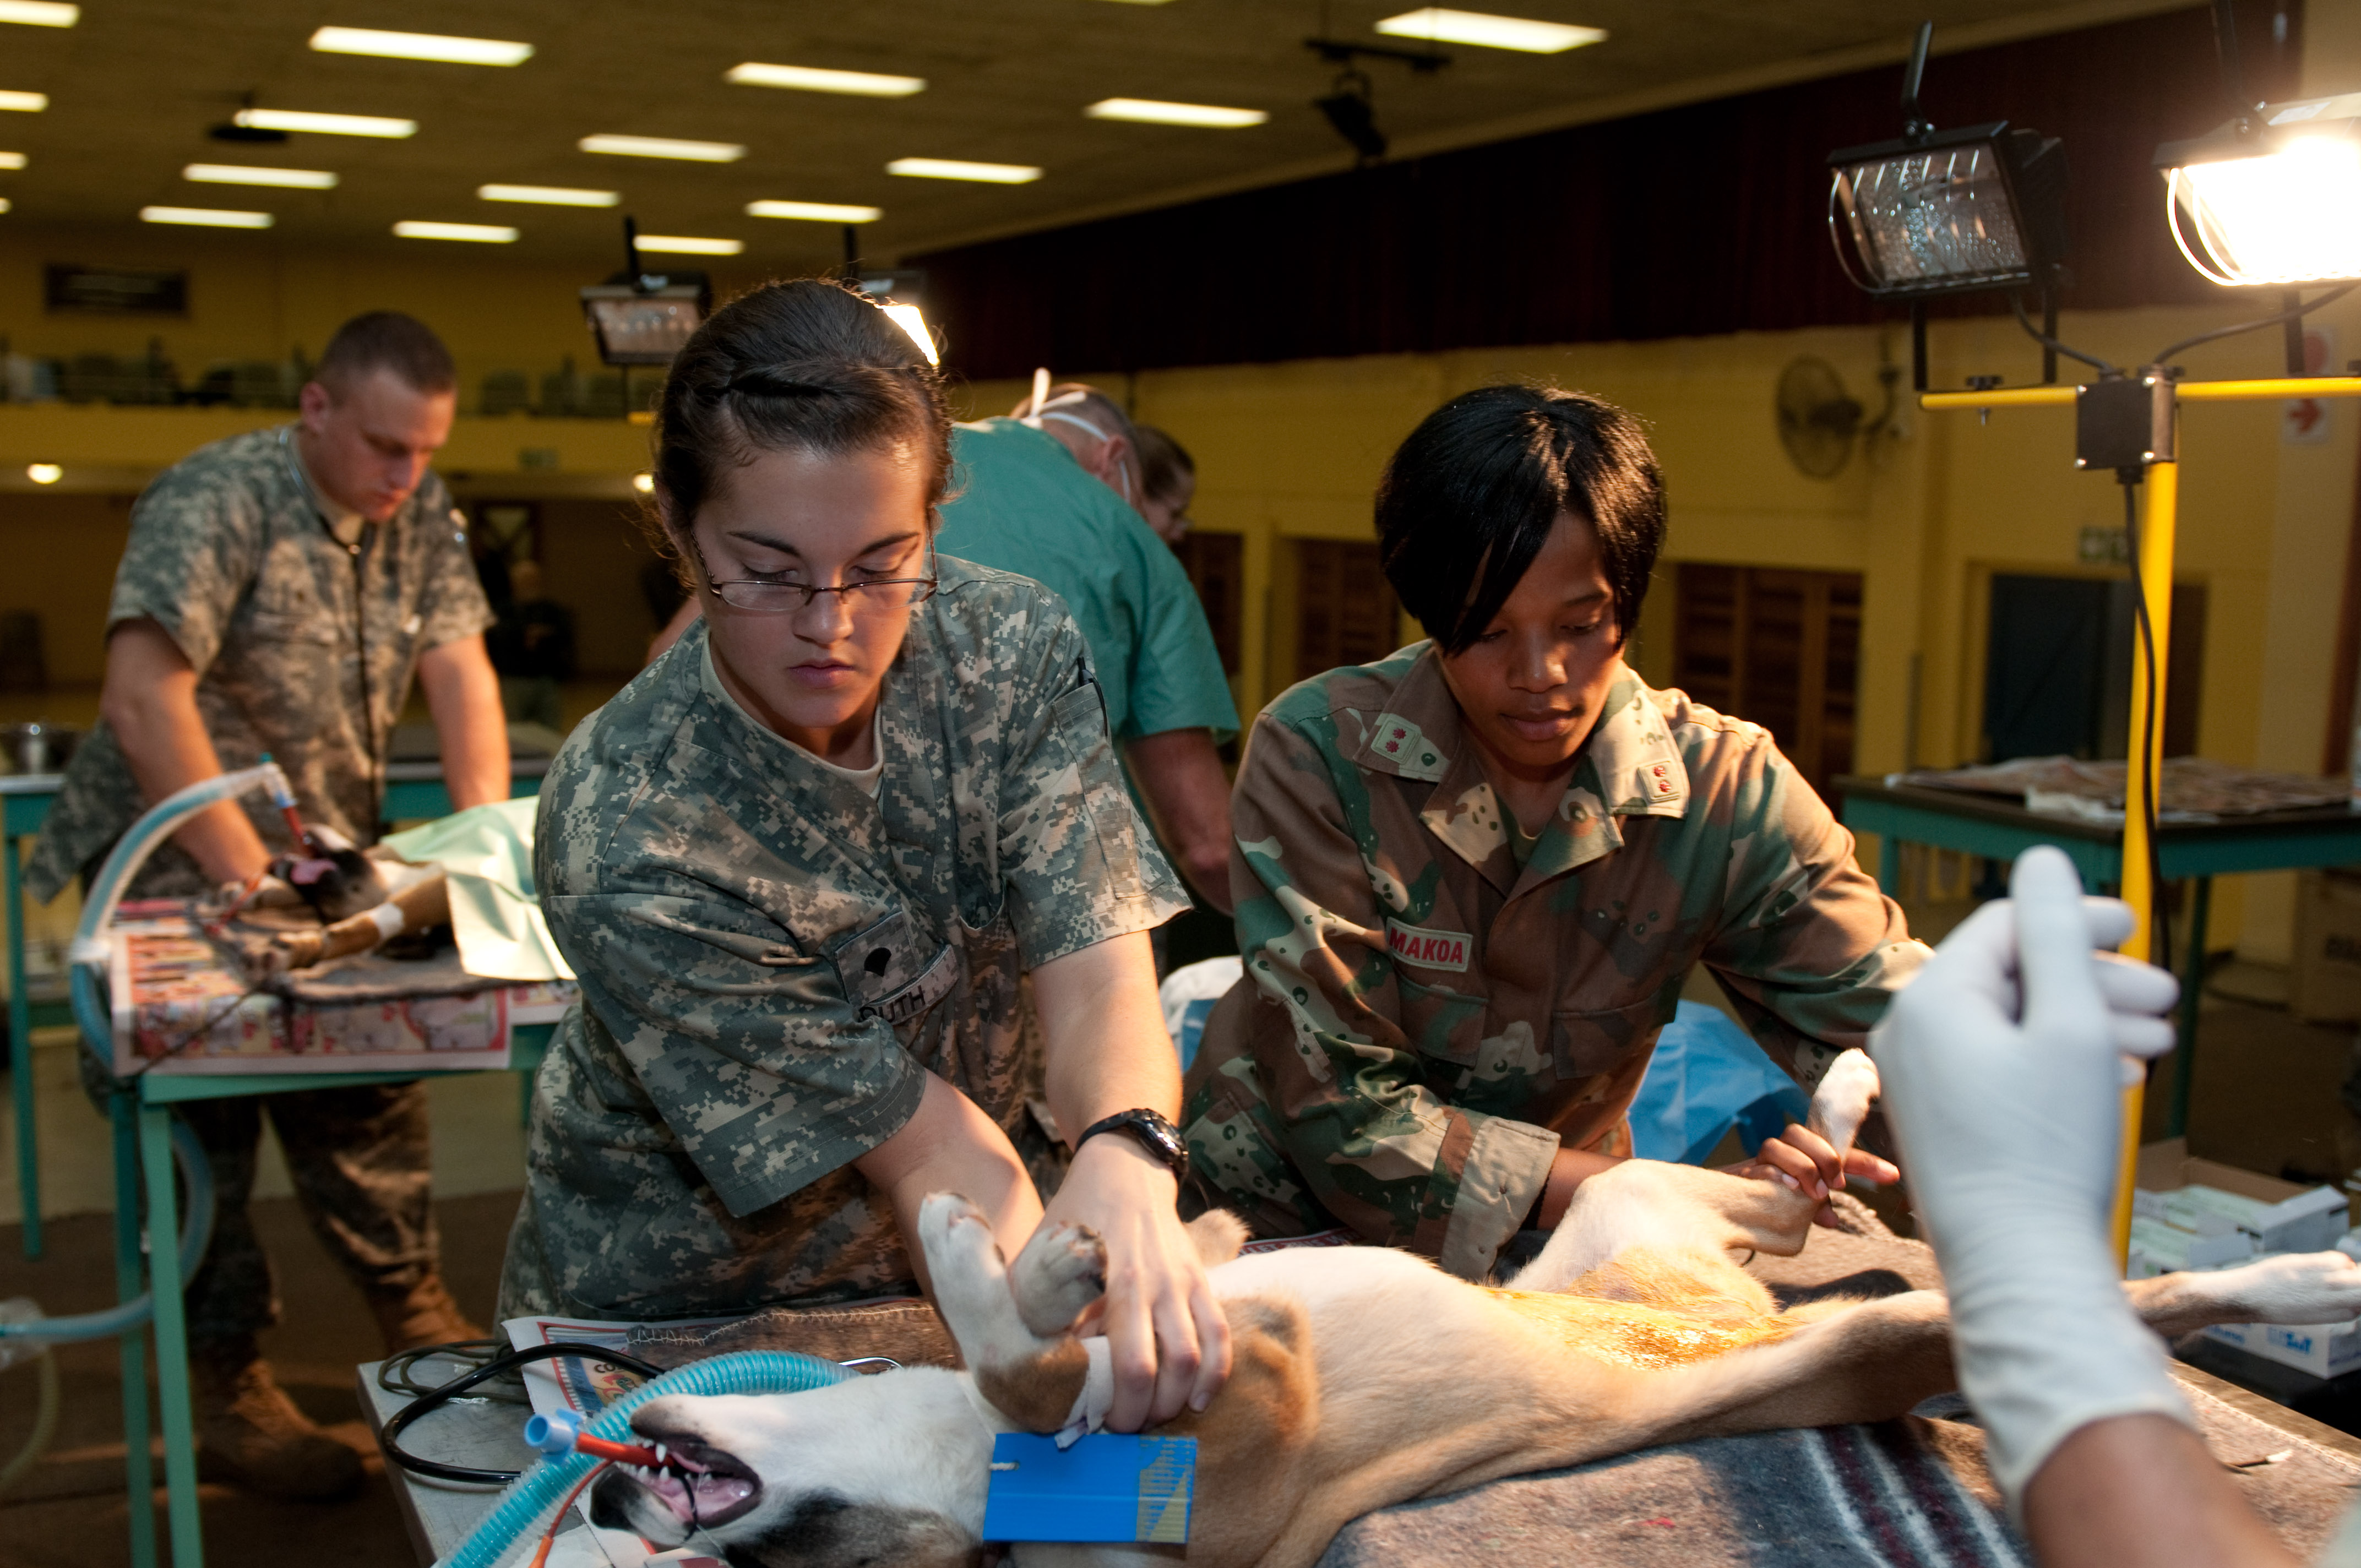
Advanced veterinary surgical and critical intensive care requires sophisticated technological infrastructure and specialized clinical teams, yet unlike human managed-care health insurance (such as HMOs and PPOs) that rely on direct provider-to-insurer billing networks, veterinary medical insurance operates predominantly on an indemnity reimbursement structure. The pet guardian pays the attending veterinary hospital directly upon discharge, subsequently submitting itemized clinical invoices and full medical SOAP notes to the underwriter for adjudicated cash reimbursement.
Deconstructing the three core levers of policy configuration dictates financial protection:
- Annual Deductible vs Per-Incident Deductible: An annual deductible requires the policyholder to satisfy a single upfront threshold (typically $250, $500, or $1,000) once per policy year, regardless of how many distinct illnesses or injuries occur. Conversely, per-condition deductibles require paying the deductible separately for every unique medical diagnosis throughout the animal’s lifespan, which severely disadvantages patients suffering from multiple concurrent chronic conditions.
- Reimbursement Percentages: Most modern underwriters offer coverage tiers spanning 70%, 80%, or 90% of eligible veterinary fees after the deductible is satisfied. Selecting a 90% tier minimizes out-of-pocket financial exposure during multi-thousand-dollar emergency hospitalizations while moderately raising monthly premiums.
- Annual Benefit Caps vs Unlimited Payouts: Traditional lower-tier policies enforce annual reimbursement caps (e.g., $5,000 to $10,000 per year) or individual bodily system restrictions. Comprehensive modern veterinary policies provide uncapped lifetime or annual limits, preventing catastrophic financial abandonment during protracted oncological radiation or prolonged intensive care ventilatory support.
A critical underwriting distinction involves the calculation methodology for reimbursements. Superior policies reimburse based on the actual veterinary invoice. Substandard policies calculate payouts against a proprietary “usual and customary fee” schedule, which frequently underestimates localized metropolitan emergency veterinary fees, shifting unexpected out-of-pocket burdens back onto the consumer.
2. Pre-Existing Conditions, Waiting Periods, and the Medical Record Lookback
Tertiary veterinary surgical interventions and emergency stabilization generate substantial clinical expenditures that exceed standard domestic emergency savings, but the single most pervasive source of insurance claim disputes and policy dissatisfaction stems from the universal exclusion of pre-existing conditions. In veterinary insurance underwriting, any clinical sign, symptom, diagnostic inquiry, or illness documented in the patient’s veterinary medical records prior to policy inception or during the designated waiting period is permanently deemed pre-existing and ineligible for coverage.
Policyholders must navigate strict underwriting waiting periods:
- Accident Waiting Periods: Typically spanning 48 to 72 hours following policy activation, covering sudden traumatic injuries such as motor vehicle collisions, acute lacerations, and foreign body ingestions.
- Illness Waiting Periods: Universally mandated at 14 days, designed to prevent adverse selection where owners purchase insurance after observing initial prodromal disease signs (such as subtle weight loss or soft stools).
- Orthopedic & Cruciate Exclusion Windows: Due to extreme actuarial claims for canine cranial cruciate ligament (CCL) tears and hip dysplasia, insurers enforce extended waiting periods ranging from six to twelve months for orthopedic conditions unless an authorized veterinary orthopedic examination certifies joint stability during policy onboarding.
A hidden contractual hazard that catches countless policyholders off-guard is the Bilateral Condition Exclusion. In large, active, or sporting dog breeds, when one cranial cruciate ligament ruptures, compensatory biomechanical overload shifts onto the opposite hindlimb, resulting in a 40% to 50% statistical probability of contralateral CCL rupture within 18 months. Crucially, many standard policy terms contain fine-print bilateral exclusion clauses: if a dog exhibited even subtle unilateral hindlimb stiffness, minor lameness, or mild stifle osteoarthritis on one leg (e.g., right stifle) prior to enrollment or during the 6- to 12-month orthopedic waiting period, the underwriter classifies any subsequent rupture of the opposite leg (left stifle) as part of a single pre-existing bilateral condition. Consequently, claims for both limbs are permanently denied, leaving the guardian with over $10,000 to $13,000 in out-of-pocket bilateral Tibial Plateau Leveling Osteotomy (TPLO) costs. Guardians must meticulously examine the policy wording prior to enrollment to ensure the insurer explicitly covers bilateral conditions as separate, distinct medical events rather than enforcing blanket bilateral exclusions.
| Clinical Emergency Category | Representative Procedures & Protocols | Average Tertiary Cost Spectrum | Actuarial Probability & Mortality Impact |
|---|---|---|---|
| Acute Gastric Dilatation-Volvulus (GDV) | Emergency trocharization, exploratory laparotomy, gastropexy | $4,500 – $8,500 | Deep-chested large breeds (Great Dane, Weimaraner); hyper-acute fatality without immediate surgery |
| Cranial Cruciate Rupture (CCL / TPLO) | Tibial Plateau Leveling Osteotomy, post-op physical rehabilitation | $4,000 – $6,500 (Per individual limb) | High-drive sporting breeds; 50% probability of contralateral limb rupture within 18 months |
| Feline Urethral Obstruction (FLUTD) | TomCat catheterization, 72h ICU diuresis, PU perineal urethrostomy | $2,800 – $5,500 | Male domestic cats; extreme hyperkalemic cardiac arrest hazard without prompt unblocking |
| Foreign Body Obstruction (GI Surgery) | Endoscopic retrieval, enterotomy, intestinal resection & anastomosis (R&A) | $3,200 – $7,000 | Juvenile and power-chewer canines; high recurrence rate in pica-prone individuals |
3. Evaluating Policy Tiers: Accident-Only vs Comprehensive vs Wellness Riders
Regular preventative wellness examinations establish an accurate baseline in patient medical charts, protecting future claims eligibility, but choosing the proper insurance tier dictates whether long-term policy retention remains financially feasible. The financial mechanics driving policy abandonment (lapsing) stem from two compounding forces: general inflation and veterinary medical inflation.
Unlike standard consumer price index inflation (CPI 2% to 3%), veterinary medical inflation (Veterinary CPI) compounds at 8% to 12% annually due to capital investments in cutting-edge diagnostic technology (CT, MRI, ICU telemetry) and specialized clinical clinician compensation. When an insured companion animal reaches senior life stages (age 8+), this annual Veterinary CPI is compounded exponentially by the insurer’s actuarial age-escalation factor. Consequently, a comprehensive policy premium that began at an affordable $45 per month during puppyhood predictably skyrockets to $200 to $350 or more per month by age 9 or 10. Guardians facing these sudden price spikes are frequently forced to cancel their coverage at the exact senior phase when catastrophic diseases (oncology, chronic renal failure, cardiomyopathy) are statistically most prevalent.
To defend against this compounding financial burden, savvy guardians implement a hybrid risk-hedging strategy. During young adulthood (ages 1 to 6), maintain a comprehensive policy with a low deductible ($250 to $500) and 90% reimbursement to absorb active pediatric and adult hazards. Then, upon entering senior life stages (ages 7 to 8), restructure the policy into a Catastrophic High-Deductible tier ($1,000 annual deductible paired with 80% reimbursement). This restructuring immediately suppresses exorbitant monthly premium spikes, while the monthly premium savings are channeled directly into a dedicated, high-yield veterinary emergency sinking fund. The guardian self-insures for routine outpatient visits while maintaining full casualty protection against catastrophic multi-thousand-dollar crises.
| Policy Classification | Coverage Scope & Clinical Inclusions | Target Patient Demographics | Cost-Benefit Tradeoff & Actuarial Rating |
|---|---|---|---|
| Accident-Only Plan | Motor vehicular trauma, bone fractures, bite lacerations, acute foreign bodies | Senior pets with extensive disqualifying pre-existing illness records | Lowest premium ($15–$25/mo); zero coverage for cancer, diabetes, or renal failure |
| Comprehensive Accident & Illness | Emergency surgeries, oncology, systemic disease, advanced imaging, Rx drugs | Puppies, kittens, and healthy adult companion animals (< 6 years) | Gold standard casualty protection ($45–$90/mo); fully shields against catastrophic tertiary bills |
| Wellness / Routine Care Rider | Core vaccinations, microchips, dental prophylaxis, annual blood screens | Guardians seeking predictable monthly budgeting for routine care | Pre-paid budgeting plan ($20–$35/mo); premium frequently equals benefit cap (0% risk transfer) |
| Catastrophic High-Deductible Tier | Full accident & illness coverage paired with $1,000 Deductible / 90% Tier | Budget-conscious handlers protecting exclusively against >$3,000 crises | Optimal financial leverage ($30–$55/mo); guardian absorbs minor clinic visits |
Veterinary Insurance Actuarial & Out-of-Pocket Triage Simulator
Quantify out-of-pocket financial liability, claim reimbursement percentages, age-escalation premiums, and bilateral exclusion exposure across canine and feline breeds.
Actual Invoice Adjudication
Underwriting Model: Post-Treatment Indemnity Reimbursement
Guardian Out-of-Pocket: $875 (13%)
Calculated on Eligible Actual Incurred Veterinary Expenses
100% (Complete Risk Transfer)
4. Actuarial Breed Risk Profiles and Lifespan Financial Modeling
Insurance underwriting algorithms determine monthly premium pricing through complex actuarial equations that quantify the statistical probability and projected cost of future medical claims. Guardians must recognize that premiums are never static; they rise systematically as patients age and veterinary medical inflation compounds.
Four primary actuarial variables govern policy pricing:
- Species Disparities: Canine policies consistently price 30% to 60% higher than feline policies. Dogs possess higher body mass requiring larger pharmaceutical dosages, engage in outdoor activities with elevated orthopedic trauma incidence, and demonstrate higher rates of foreign body ingestion.
- Breed-Specific Hereditary Risk: Brachycephalic breeds (such as French Bulldogs and Pugs) carry astronomical premium loadings due to near-universal incidences of Brachycephalic Obstructive Airway Syndrome (BOAS), hemivertebrae, and spinal disc disease. Similarly, Golden Retrievers and Boxers trigger higher rates due to extreme oncological predispositions.
- Geographic Veterinary Fee Indexing: Actuarial pricing directly reflects the postal code of the primary residence. Veterinary surgical overhead, staff salaries, and diagnostic infrastructure costs in high-density metropolitan areas (such as New York City, San Francisco, or Los Angeles) are double those of rural regions, resulting in significantly higher baseline premiums.
- Age-Related Exponential Escalation: Claims probability does not climb linearly; it accelerates exponentially beyond seven to eight years of age as chronic degenerative diseases (osteoarthritis, renal disease, cardiac failure) manifest, requiring serial pharmacotherapy and ongoing diagnostics.
Rigorous financial analysis confirms that routine wellness riders rarely yield positive financial returns. Most wellness riders charge between $20 and $35 per month ($240 to $420 annually) while enforcing strict per-procedure reimbursement caps. In the majority of actuarial scenarios, cumulative annual premiums paid for the rider equal or exceed total clinical reimbursements received. Optimal capital allocation prioritizes high-coverage comprehensive emergency policies with uncapped benefits, while self-insuring for routine wellness checks.
5. Strategic Claims Management: Dispute Resolution and Medical Record Optimization
Navigating the insurance claim lifecycle requires a methodical, analytical approach to eliminate claim denials and maximize adjudicated reimbursements:
- Enroll During the Pediatric Window: Obtain comprehensive coverage within the first eight to twelve weeks of life, immediately following the initial veterinary intake examination. Securing insurance before the onset of chronic ear infections, skin allergies, or digestive upsets ensures that future manifestations of these lifelong conditions remain fully covered.
- Audit Full Medical Records Prior to Enrollment: Request a complete copy of all historical veterinary medical records, including technician notes and intake forms. Review the charts to identify any documented symptoms that underwriters could classify as pre-existing, allowing you to select underwriters with favorable pre-existing condition curable clauses (many underwriters reinstate coverage for “cured” conditions after 180 to 365 symptom-free days).
- Select an Annual Deductible with 80% to 90% Reimbursement: Configure the policy with an annual deductible ($500 represents the optimal balance between affordable monthly premiums and realistic claim thresholds) paired with an 80% or 90% reimbursement rate on actual veterinary bills.
- Establish a Dedicated Emergency Card or Credit Line: Because insurance operates via post-treatment reimbursement, hospitals require full payment upon patient discharge. Maintain a dedicated high-limit credit line (such as CareCredit or a low-interest credit card) to bridge the cash flow window between hospital discharge and claims disbursement.
By treating pet health insurance as a calculated risk-transfer instrument rather than a discount coupon, caregivers insulate their families from devastating financial dilemmas and ensure uncompromising medical advocacy for their beloved companion animals.